2026 European PHEV Market Report: Registration Stats Across the Big 5 & the Chinese Automaker Disruption
As plug-in hybrids capture a 10% market share across Europe, the exclusion of PHEVs from the EU's countervailing EV tariffs has provided Chinese automakers with an unprecedented tariff arbitrage. We analyze official registration data and sales podiums across Poland, Spain, Italy, Germany, and France.
The European Union passenger car market in 2026 is experiencing a structural transformation triggered by stringent regulatory pressures, national fiscal policies, and shifting powertrain dynamics. Official registration statistics compiled by the European Automobile Manufacturers’ Association (ACEA) and national motor transport authorities confirm that alternative-fuel vehicles now account for the lion's share of new registrations, while conventional internal combustion engines (petrol and diesel) continue double-digit declines.
Within this electrified landscape, plug-in hybrid electric vehicles (PHEVs) have solidified their role as a critical bridge technology, commanding a steady 9.1% to 10.0% market share across the EU.
Critical Tariff Arbitrage: The Exemption from Anti-Subsidy BEV Countervailing Duties
The single most transformative market dynamic in 2026 is the rapid ascent of Chinese automotive manufacturers (BYD, Chery Group's Omoda and Jaecoo, SAIC's MG, Stellantis-partnered Leapmotor, and Geely) across the European PHEV landscape.
When the European Commission finalized its definitive countervailing duties on battery electric vehicles (BEVs) imported from China (additional duties of 17.0% for BYD, 18.8% for Geely, and 35.3% for SAIC on top of the standard 10% base duty), plug-in hybrid powertrains were notably excluded.
Subject solely to the baseline 10% WTO import tariff, PHEVs became the optimal expansion vector for Chinese automakers. By offering highly equipped, long-range C- and D-segment SUVs at price points legacy European OEMs struggle to match, Chinese plug-in hybrids have reshaped regional sales rankings.
1. Poland: Total Dominance of Chinese Automakers in the PHEV Segment
According to official figures from the Polish Automotive Market Research Institute (IBRM SAMAR) and the Central Vehicle Register (CEPiK), new passenger car registrations in Poland reached 368,236 units during the first seven months of 2026 (January–July), up 9.7% year-on-year.
The standout growth segment was plug-in hybrids, which nearly doubled in volume. After recording 15,995 registrations across the entirety of 2024 (with zero Chinese models in the top 20), Polish PHEV sales surged by 97.7% YoY in Jan–Jul 2026 to 31,874 units.
| Metric (Poland - Jan–Jul 2026) | Official Value (IBRM SAMAR / CEPiK) |
|---|---|
| Total Passenger Car Registrations | 368,236 units (+9.7% YoY) |
| Electrified Powertrain Registrations (HEV/MHEV/PHEV/BEV) | 234,724 units (63.7% market share) |
| Total PHEV Registrations | 31,874 units (+97.7% YoY) |
| PHEV Segment Market Share | 8.7% |
| Pure Electric (BEV) Registrations | 18,737 units (+3.7% YoY) |
| Chinese Brand Share in PHEV Segment | Approx. 37% – 40% |
| Chinese Brand Share in Total Market (Jan–Apr) | 11.6% (23.5k units) |
In Poland's PHEV brand standings, Chinese manufacturers seized the entire podium:
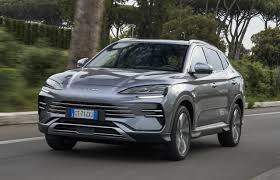
- BYD finished as the undisputed market leader with 5,051 registrations (~16% market share).
- Chery Group followed in second place with 3,974 units.
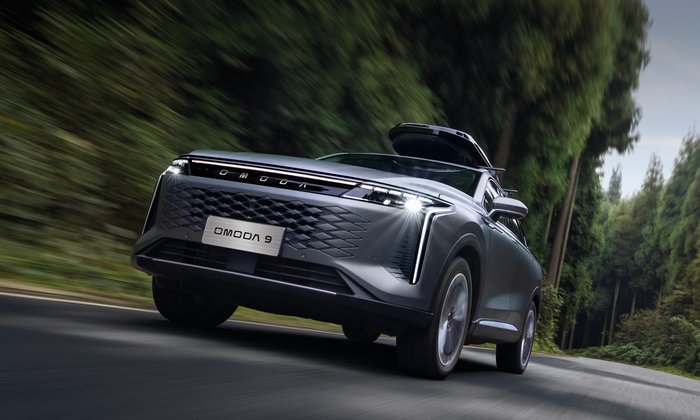
- Omoda took third with 3,440 registrations.
Polish PHEV Model Ranking (January–July 2026)
| Rank | Model | Volume | Origin / Segment |
|---|---|---|---|
| 1 | BYD Seal U DM-i | 2,906 – 2,913 units | China / D-SUV Plug-in Hybrid |
| 2 | Omoda 9 PHEV | 2,880 units | China / D-SUV Plug-in Hybrid |
| 3 | Jaecoo 7 PHEV | 1,540 units | China / C-SUV Plug-in Hybrid |
The structural driver in Poland is sharp consumer price sensitivity: in the 100,000 to 150,000 PLN budget bracket, legacy European OEMs predominantly offer compact petrol hatchbacks or mild hybrids. Chinese brands deliver fully-loaded D-SUVs featuring panoramic sunroofs, ADAS suites, and 80+ km WLTP electric ranges for the exact same budget.
2. Spain: Mediterranean Electrification & Chinese Podium Sweep
Data from the Spanish Association of Automobile and Truck Manufacturers (ANFAC) and the Directorate-General for Traffic (DGT/IDEAUTO) position Spain as one of Europe's fastest-accelerating electrification markets in 2026. The widespread enforcement of Low Emission Zones (ZBE) across Spanish metropolitan centers has steered buyers toward vehicles carrying the coveted "CERO Emisiones" badge, which confers free urban access and parking exemptions.
During the January–August 2026 period, the Spanish PHEV market expanded by 35.0% YoY to 105,396 registrations, boosting PHEV penetration to 13.0% of all passenger car sales. In August 2026 alone, 9,768 PHEVs were registered (+23.3% YoY).
| Metric (Spain - 2026 Cumulative / August) | Official Value (ANFAC / DGT) |
|---|---|
| Jan–Aug 2026 Total PHEV Registrations | 105,396 units (+35.0% YoY) |
| PHEV Passenger Car Market Share (Jan–Aug) | 13.0% |
| August 2026 Single Month PHEV Registrations | 9,768 units (+23.3% YoY) |
| Electrified Fleet Share (HEV + PHEV) | Approx. 60% |
Spanish PHEV Model Ranking (August 2026)
| Rank | Model | August 2026 Units | Origin / Powertrain |
|---|---|---|---|
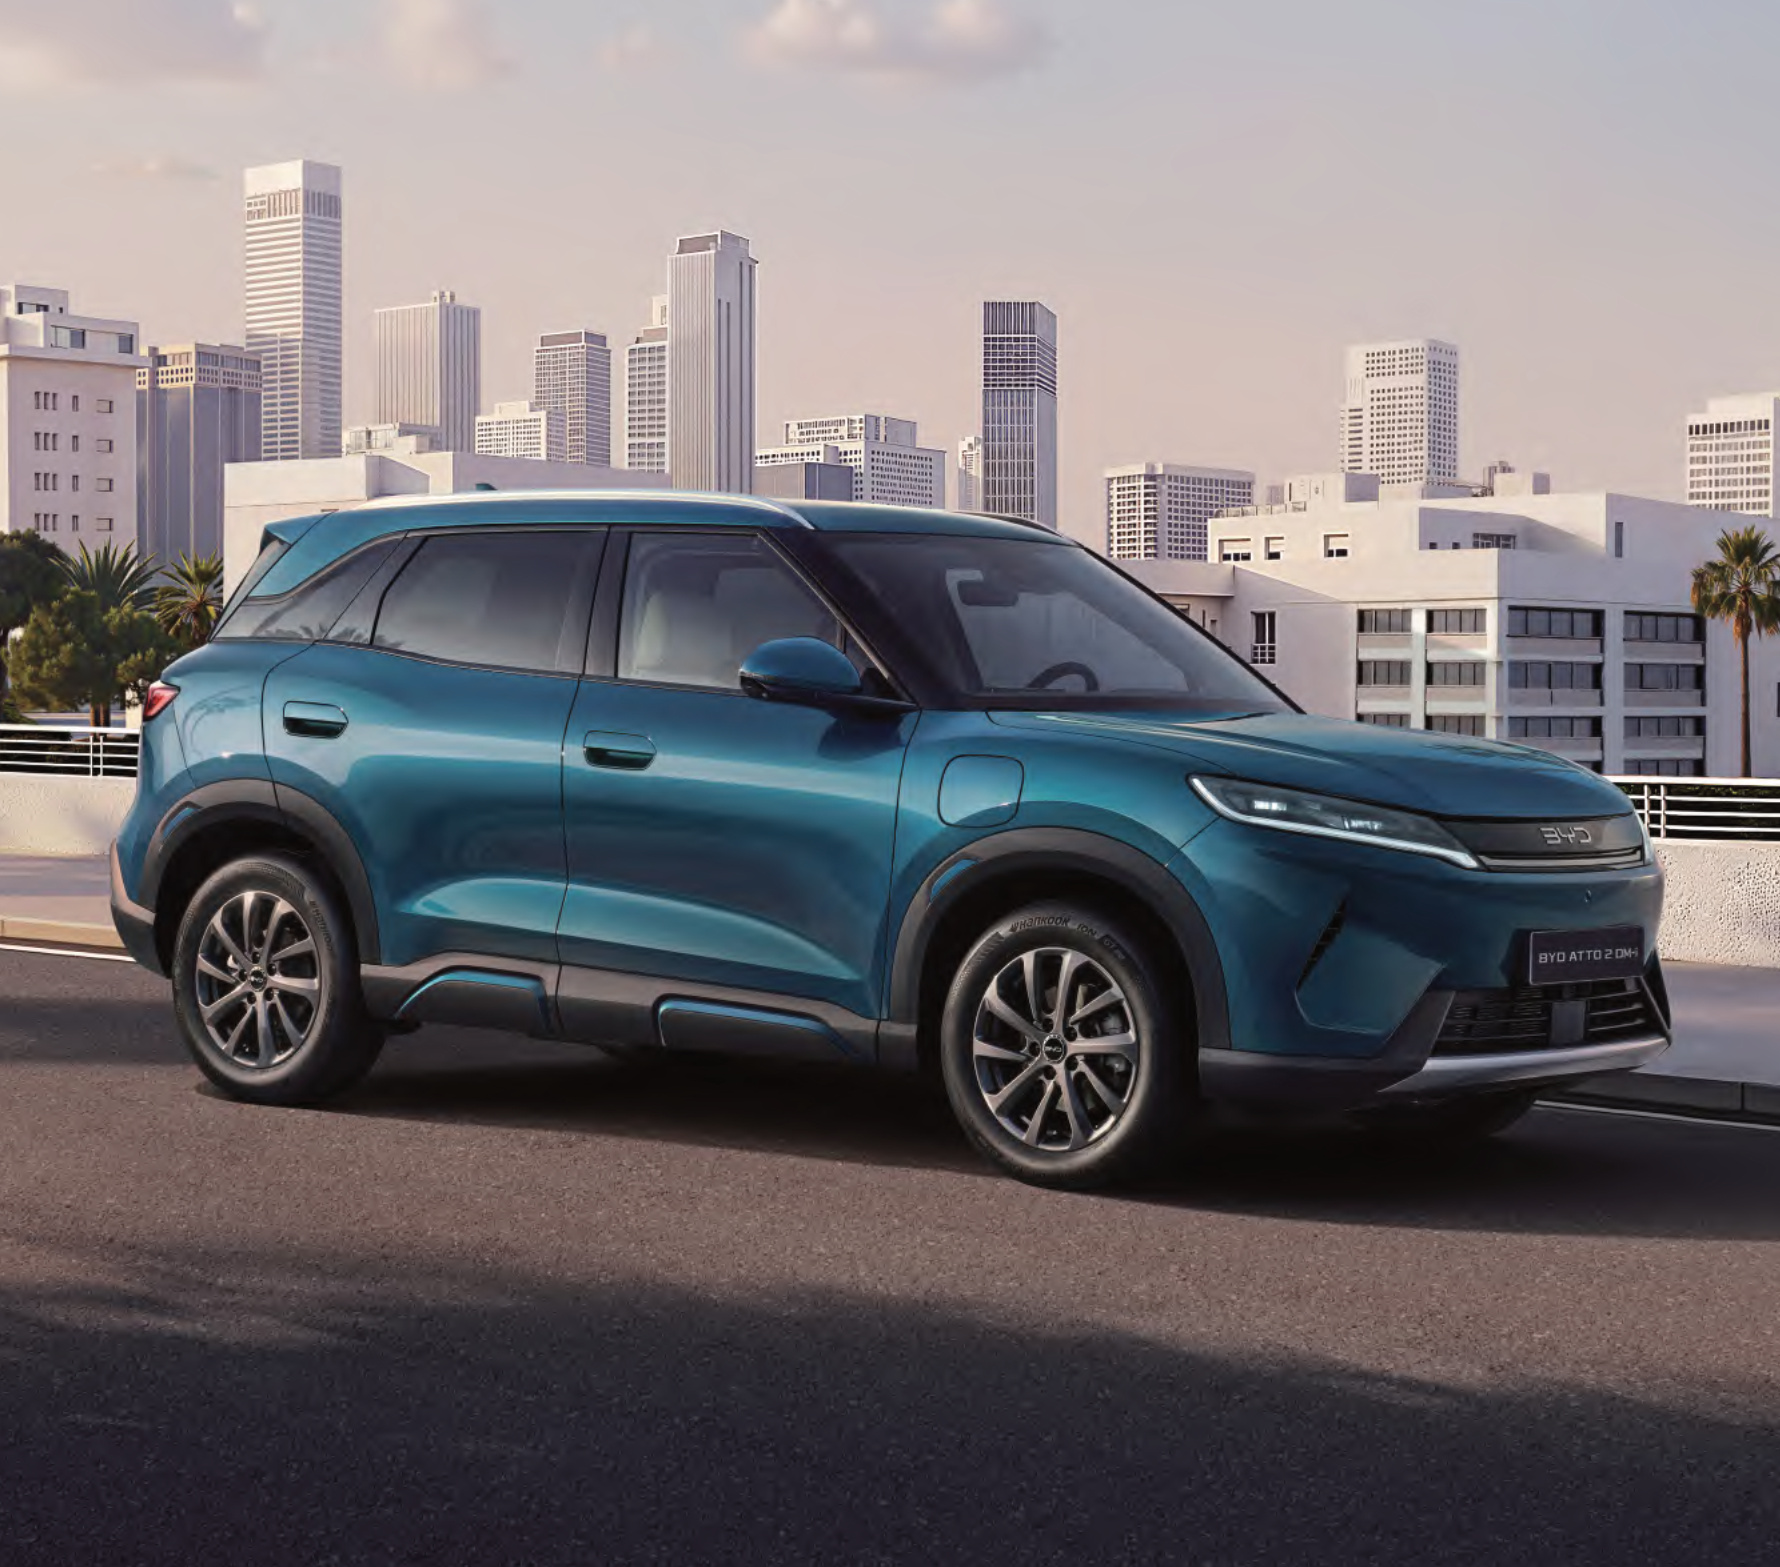
| 1 | BYD Atto 2 DM-i | 783 units | China / B-SUV Plug-in Hybrid |
| 2 | BYD Seal U DM-i | 581 units | China / D-SUV Plug-in Hybrid |
| 3 | Geely Starray EM-i | 574 units | China / C-SUV Plug-in Hybrid |
| 4 | Toyota RAV4 PHEV | 445 units | Japan / D-SUV Plug-in Hybrid |
| 5 | Toyota C-HR PHEV | 441 units | Japan / C-SUV Plug-in Hybrid |
| 6 | BYD Dolphin G | 382 units | China / Compact Hatchback |
| 7 | Ebro S700 PHEV | 338 units | Spain-China Joint Assembly (Chery Barcelona) |
| 8 | Mercedes-Benz GLC PHEV | 334 units | Germany / Premium D-SUV |
| 9 | Volkswagen Tiguan eHybrid | 277 units | Germany / C-SUV |
| 10 | Ford Kuga PHEV | 249 units | USA-Spain Built / C-SUV |
Local assembly at the revitalized former Nissan plant in Barcelona by Chery and its Spanish partner Ebro propelled the Ebro S700 PHEV straight into the top 10, while the formerly dominant Ford Kuga dropped to 10th position.
3. Italy: Corporate Fleet Tax Incentives & Registration Surges
According to the National Union of Foreign Automobile Representatives (UNRAE) and the Italian Ministry of Infrastructure and Transport, Italian passenger car registrations totaled 1,268,964 units (+8.7% YoY) through the first nine months of 2026.
The primary catalyst for PHEV expansion in Italy has been targeted corporate taxation reform. While company cars with combustion engines carry a 50% taxable fringe benefit baseline, the Italian tax code reduces this liability to just 20% for PHEVs (and 10% for BEVs). With over 40% to 45% of all PHEVs registered through long-term corporate rental (NLT) channels, fleet procurement officers have massively transitioned to plug-in hybrids.
| Metric (Italy - 2026 Cumulative / September) | Official Value (UNRAE / MIT) |
|---|---|
| Jan–Sep 2026 Total Passenger Car Registrations | 1,268,964 units (+8.7% YoY) |
| PHEV Market Share (Jan–Jul Cumulative) | 9.2% |
| PHEV Market Share (September 2026 Single Month) | 10.8% – 11.1% |
| PHEV Annual Volume Growth (YoY) | +78.0% to +99.2% |
| Long-Term Rental (NLT) Share of PHEV Sales | >40% – 45% |
Italian PHEV Model Ranking (September 2026)
| Rank | Model | September 2026 Volume | Market Dynamics |
|---|---|---|---|
| 1 | BYD Seal U DM-i | ~2,144 units | Overall Top 50 passenger car (#13 rank across all powertrains) |
| 2 | BYD Atto 2 DM-i | 1,373 units | Italy's #1 cumulative PHEV in 2026 (>16,000 units YTD) |
| 3 | Leapmotor B10 | 914 units | C-SUV distributed via the Stellantis dealer network |
| 4 | Geely Starray | 686 units | Rapidly rising compact hybrid crossover |
| 5 | BMW X1 PHEV | 551 units | German premium executive favorite |
| 6 | Jaecoo 7 PHEV | 544 units | Chery Group off-road styled PHEV |
| 7 | Volkswagen Tiguan eHybrid | 511 units | Standard corporate fleet stalwart |
| 8 | Audi Q3 TFSI e | 493 units | Premium compact crossover |
| 9 | Omoda 9 PHEV | 471 units | High-spec flagship D-SUV |
| 10 | BYD Dolphin G | 435 units | Accessible urban plug-in option |
BYD’s cumulative Italian volume reached 36,000 units through August 2026, advancing to 13th overall among all car brands in Italy (+194% YoY).
4. Germany: Federal Market Resilience & KBA Registration Jumps
The Federal Motor Transport Authority (Kraftfahrt-Bundesamt - KBA) recorded approximately 1,488,000 new passenger car registrations in Germany during the first half of 2026 (Jan–Jun). Plug-in hybrids maintained double-digit growth, underpinned by Germany’s 0.5% Dienstwagen (company car) tax assessment for vehicles with sub-50g CO2 ratings or 80+ km EV ranges.
In Q1 2026, German PHEV registrations rose 19.3% YoY to 76,114 units (10.9% market share). In June 2026 alone, 32,212 PHEVs were registered (+25.8% YoY).
Chinese OEM Performance in Germany (KBA 2026)
- BYD: 26,252 units (Jan–Jun) / 31,492 units (Jan–Jul), reflecting +315.2% YoY growth. In July, BYD registered 5,240 vehicles, surpassing Tesla in monthly registrations.
- SAIC (MG / Roewe): 16,152 units (Jan–Jun) / 19,850 units (Jan–Jul), up +40.2% YoY.
- Leapmotor: 8,402 units (Jan–Jun), expanding by +306.5% YoY through established Stellantis dealerships.
- Chery (Omoda / Jaecoo): Rapidly expanding retail footprint, onboarding over 50 German dealer groups.
The BYD Seal U DM-i solidified its position as one of Germany's most popular plug-in crossovers, frequently topping alternate-powertrain monthly breakdowns.
5. France: Stricter Fiscal Headwinds, Weight Penalties & Leasing Social
In France, data from the French Automotive Platform (PFA) and AAA Data show 1,234,952 new passenger car registrations through September 2026 (+4.06% YoY). However, France diverged sharply from the rest of the continent in its powertrain mix.
On January 1, 2026, France's revised environmental fiscal regime introduced:
- Lowered Malus CO2 threshold: Tightened from 113 g/km to 108 g/km.
- Lowered Weight Penalty (Malus au Poids): Weight threshold decreased from 1,600 kg to 1,500 kg.
Heavier plug-in hybrids faced steep registration surcharges. Concurrently, the state-backed "Leasing Social" program—offering heavily subsidized EV leases to low-income households—channeled consumer demand directly toward European-built compact BEVs.
| Metric (France - 2026 Trends) | Official Value (PFA / AAA Data / Avere) |
|---|---|
| Jan–Sep 2026 Total Registrations | 1,234,952 units (+4.06% YoY) |
| BEV Market Share Progression | 31.9% (July) → 35.33% (August) → 42.0% (September) |
| PHEV Market Share | 5.2% – 6.0% band |
| September 2026 PHEV Registrations | 10,028 units (+10.0% YoY) |
| Chinese Automaker Market Share | 8.0% – 9.67% band |
Consequently, the French PHEV segment remained anchored by domestic and legacy models (Peugeot 308 PHEV, DS 7 E-Tense, Mercedes-Benz GLC PHEV), with Chinese imports primarily serving corporate fleet buyers where tax deductibility offsets the weight surcharge.
Comparative Five-Market Overview
| Country | PHEV Market Share | YoY Growth | Chinese OEM Position | Top PHEV Models (Overall / Chinese) | Key Regulatory & Fiscal Driver |
|---|---|---|---|---|---|
| Poland | 8.7% | +97.7% | Very High (Podium Sweep) | BYD Seal U DM-i, Omoda 9, Jaecoo 7 | 100k–150k PLN price sensitivity; PHEV chosen over lagging BEV charging infrastructure |
| Spain | 13.0% | +35.0% | High (Top 3 Dominance) | BYD Atto 2 DM-i, BYD Seal U DM-i, Geely Starray | DGT CERO sticker required for metropolitan ZBE zones; Chery-Ebro Barcelona plant |
| Italy | 9.2% – 11.1% | +78.0% – +99.2% | Very High (Top 4 Ranks) | BYD Atto 2 DM-i, BYD Seal U DM-i, Leapmotor B10 | 20% fringe benefit company car rate; >40% long-term corporate leasing (NLT) |
| Germany | 10.9% | +19.3% – +25.8% | Moderate-High (BYD Segment Lead) | BYD Seal U DM-i, VW Tiguan, BMW X1, Mercedes GLC | 0.5% Dienstwagen tax exemption; rapidly multiplying retail dealer networks |
| France | 5.2% – 6.0% | +4.0% – +10.0% | Limited (BEV-Driven Market) | Peugeot 308, Mercedes GLC, DS 7, BYD Seal U | Punitive Malus CO2 (108g) & Weight Tax (1,500kg); subsidized Leasing Social BEV scheme |
Conclusion & Industrialization Roadmaps
The exclusion of plug-in hybrids from EU anti-subsidy countervailing duties has triggered a substantial pivot in Chinese OEM strategy toward advanced PHEV powertrains. BYD’s "DM-i" and Chery's super-hybrid DHT architectures deliver high electric efficiency alongside zero range anxiety at competitive prices.
To mitigate future trade policy volatility, Chinese manufacturers are rapidly shifting from direct maritime exports to localized European production:
- BYD: Fast-tracking vehicle assembly at its new complex in Szeged, Hungary.
- Chery: Commencing production with Ebro at the former Nissan facility in Barcelona, Spain.
- Leapmotor: Leveraging Stellantis manufacturing capacity at the Zaragoza plant in Spain for the B10 crossover.
These major manufacturing commitments ensure that the Chinese PHEV footprint across European roads will only solidify in the years ahead.